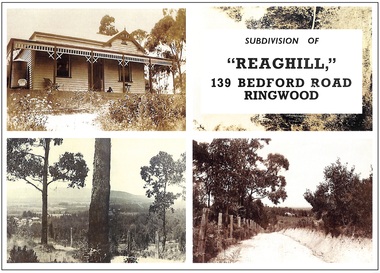
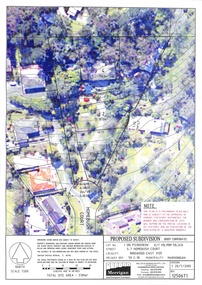
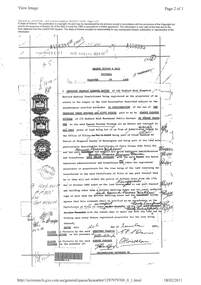
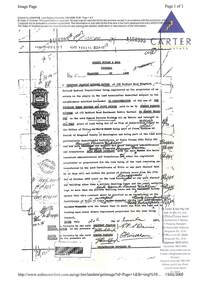
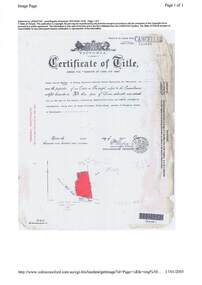
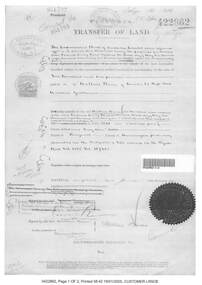
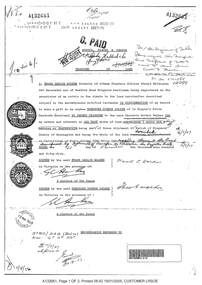
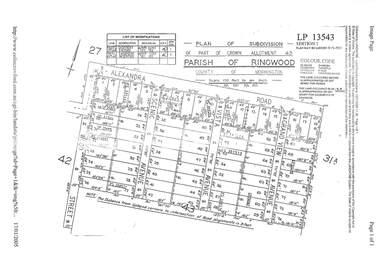
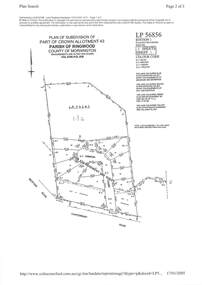
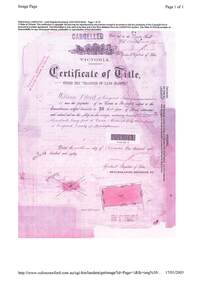
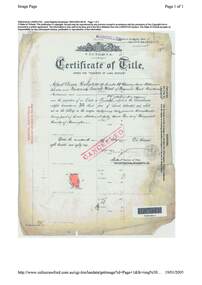
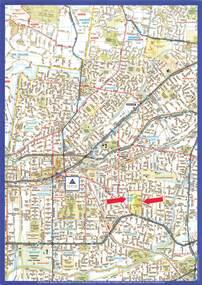
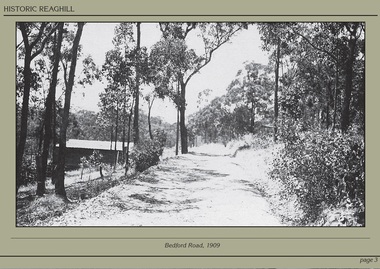
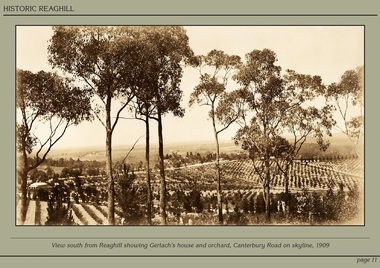
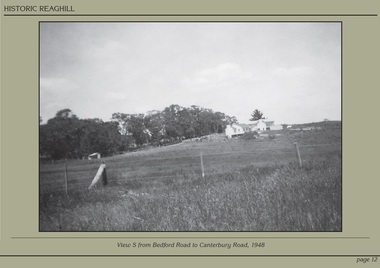
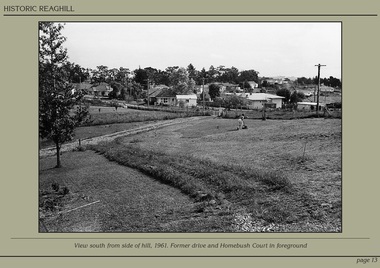
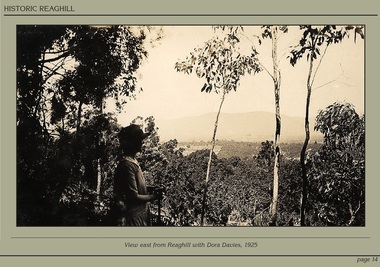
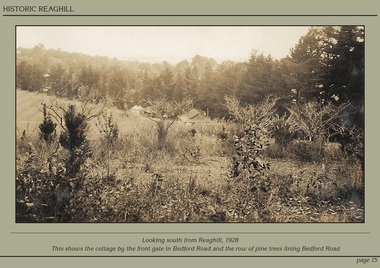
This record is the Parent Record for researching the subdivision of Reaghill, 139 Bedford Road, Ringwood, compiled by Richard Carter.
"Reaghill" is part of an older larger holding of sixty acres which came to comprise Vista Avenue, Vista Court, Homebush Court, Rawson Court and Wombalano Park
Transcript: Researching “Reaghill"
The property “Reaghill” originally stood at 139 Bedford Road, Ringwood East before the property was subdivided in the 1950s and took a new address and frontage to Vista Avenue, Ringwood East.
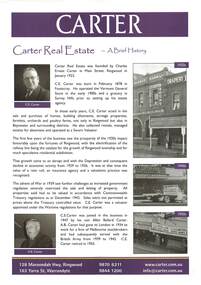
The purpose of these notes is to trace the origins of the property from the year 1900 to the present day. Information in the notes is sourced from the archives of Carter Real Estate, from Land Titles Office records and from the book of the history of Ringwood, “Ringwood, Place of Many Eagles” by Hugh Anderson.
“Reaghill” is part of an older larger holding of sixty acres. It Is the story of those 60 acres, which now comprise Vista Avenue, Vista Court, Homebush Court, Rawson Court and Wombalano Park, which Is the subject of these notes.
Earlier Times
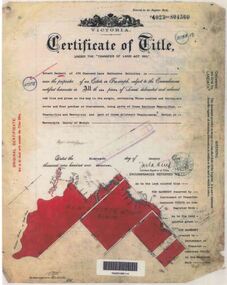
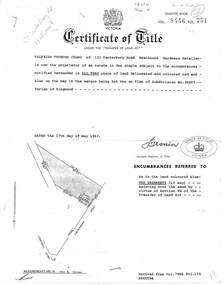
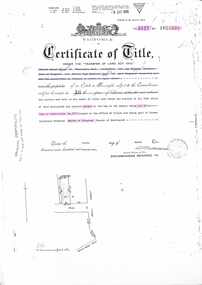
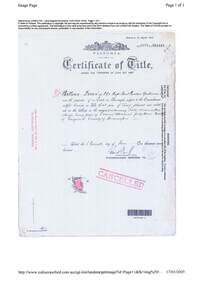
A convenient starting point for these notes Is the year 1900. On 11th June 1900 Wallace Bruce of 68 High Street, Windsor became registered as the proprietor of “sixty acres or thereabouts” (24.28 hectares) being part of Crown Allotment 43 Parish of Ringwood County of Mornington. That title. Volume 2773 Folio 485 did not name the streets to which the property abutted but clearly they were Canterbury Road at its intersection with Bedford Road.
Title records a lease of the property from Wallace Bruce to Thomas Oates, with the lease endorsed on title on 22 July 1903 and removed 16 June 1908. Wallace Bruce subsequently subdivided the land Into three parcels, two of which he sold to Dora Stanisforth Davies during 1909 and the balance he sold to Frank Leslie Walker in 1914.
The Era of the Davies
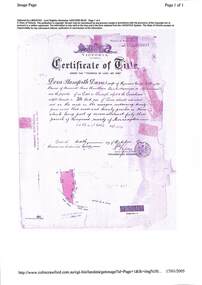
Wallace Bruce firstly sold the western portion of the property, containing twenty four acres three roods and 20 perches (24.875 acres or 10.0667 hectares) on 6 October 1909.
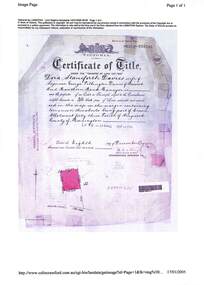
The new title, Volume 3381 Folio 021, records the new proprietor as “Dora Stanisforth Davies, wife of Seymour George Pilkington Davies of Burwood Road, Hawthorn, Bank Manager”. Shortly thereafter, Wallace Bruce sold a further parcel of “ten acres or thereabouts” (4 hectares) being the north eastern portion of his original holding. That title, Volume 3384 Folio 795, showed the purchaser once again as “Dora Stanisforth Davies, wife of Seymour George Pilkington Davies of Burwood Road Hawthorn, Bank Manager”. It is noteable that the second, title which is dated 8 December 1909, had no
abuttal to any road, nor was it at any time (even when subdivided in the 1950s) consolidated with Davies' adjoining title. Both titles then recorded that Dora Stanisforth Davies died on 19 February 1945 with probate of her will being granted to John Seymour Davies of 69 Grantham Street West Brunswick, Medical Practitioner, and Hugh Percival Hall of 339 Collins Street Melbourne, Solicitor.
Almost two years later, on 6th December 1946, both parcels of land were transferred by the Executors to Geoffrey Francis Seymour Davies of 20 Albert Road Strathfield N.S.W, Medical Practitioner.
From this chronology it could be surmised that one of Dora Davies’ executors, John Seymour Davies, was probably her son. Was Geoffrey Francis Seymour Davies another son, or was he her grandson?
In any event Geoffrey Francis Seymour Davies set about subdividing what was then the property “Reaghill” and its 34.875 acres (14.11 hectares).
The Subdivision of “Reaghill
The subdivision of “Reaghill” was made more viable by the subdivision in 1931 of the property to the north and the creation of Scenic Avenue, Vista Avenue and Grandview Avenue, all of which abutted “Reaghill’s” northern boundary. In fact Geoffrey Francis Seymour Davies bought the freehold to Grandview Avenue, Scenic Avenue and Vista Avenue in July 1955 for £84-9-0 to give him legal rights over those roads. Title to those roads and the newly created Vista Avenue, Vista Court and Homebush Court remain in his name to this day. It is particularly interesting to note that whilst those streets had typical allotments of about 1000 square metres, the subdivision of Reaghill was into blocks of one to two acres or more (4000 square metres to about one hectare) except for the blocks fronting Bedford Road. That speaks volumes about Davies’ attitude to the land, its natural beauty, its topography and vegetation.
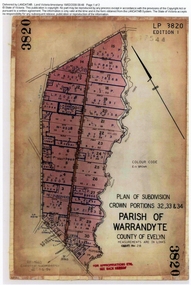
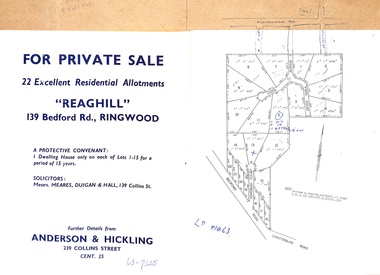
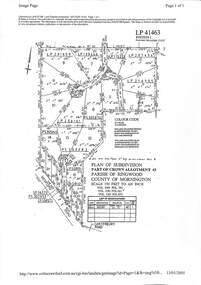
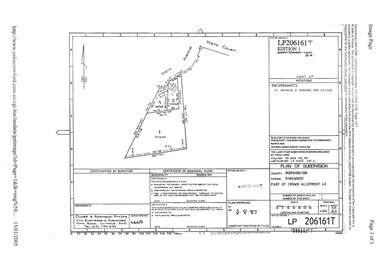
“Reaghill” was subdivided into twenty two lots by Plan of Subdivision LP 41463. The first eleven lots came off Vista Avenue and formed an extension of Vista Avenue and a newly created Vista Court. Lot sizes ranged from 1 acre 1 rood 1½ perches (5097 square metres) to 2 acres 3 roods 21½ perches (1.167 hectares). A further four lots came off Homebush Court, a newly created court off Bedford Road. Those lots ranged from 1 acre 1 rood 29 perches (5792 square metres) to 2 acres 1 rood 39 ®/io perches (1.01 hectares). Seven further lots, parallelogram in configuration, fronted Bedford Road and had a typical area of 1518 square metres. The names of the streets (“Vista” Avenue/Court and “Homebush” Court) give an insight into the elevation of the land, the views it offered and the bushland it featured.
The Covenant
As evidence of Davies’ desire to maintain the bush setting of the property, covenants were imposed on the transfers of Lots 1 to 15 (the acreage lots). That covenant allowed for only one dwelling house to be erected on each of those lots for a period of 15 years from sale. Effectively it froze subdivision for 15 years. But 15 years came around quickly.
The Sales
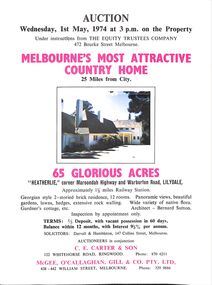
“Reaghill” 139 Bedford Road, Ringwood was offered for Private Sale as “22 Excellent Residential Allotments” by estate agents Anderson & Hickling of 239 Collins Street Melbourne (telephone Central 25!), with a “protective covenant” of one dwelling house only on lots 1-15 for a period of 15 years. Solicitors for the vendor were Messrs Meares, Duigan & Hall of 139 Collins Street Melbourne. Sales commenced in 1955 and went through to 1967. Prices were typically from £1350, the price paid for Lot 13 in 1957.
The Role of Frank Leslie Walker
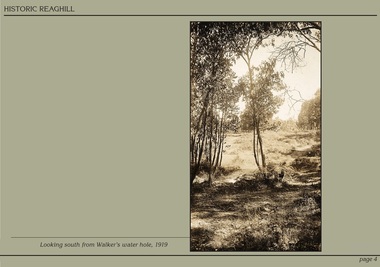
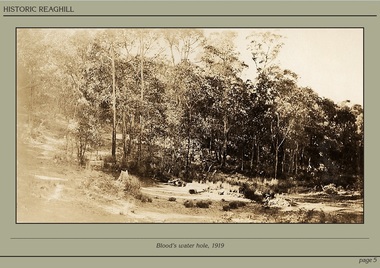
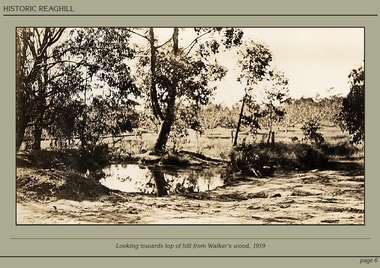
These notes have so far recorded that of the sixty acres originally owned by Wallace Bruce in 1900, some 34.875 acres were sold to Dora Davies in 1909 and subdivided and sold by her descendants. The balance of Wallace Bruce’s land was sold on 6th April 1914 to Frank Leslie Walker. This is the land at the south east corner of Bruce’s holding fronting Canterbury Road and which now comprises Rawson Court and Wombalano Park.
Frank Leslie Walker “of Albany Chambers, Collins Street Melbourne” was described as an Art Decorator. In “Ringwood - Place of Many Eagles” he is shown as living on his land “in a house which was surrounded by a four foot high brick wall and the long drive of rough cream-coloured Lilydale gravel was entered through handsome wrought iron gates obtained from some building wrecker”. The “old rambling house" had been extended and renovated using secondhand doors, windows and timber. “Every inch of wall space seemed to be crammed from floor to ceiling with oils, watercolours, etchings and drawings of all sorts by
well known artists”. On 13th August 1954 Frank Leslie Walker transferred an area of 12 acres 3 rood 21 perches (5.213 hectares) to The Mayor Councillors and Burgesses of the Borough of Ringwood for no consideration as a Gift “for the providing of pleasure grounds on places of public resort or public recreation”. That is now Wombalano Park. The balance of his property, containing 6 acres 1 rood 5 perches (2.54 hectares) and including the original homestead (named Wombalano?) was gifted by Frank Leslie Walker to his nephew on 25 November 1955. It was later subdivided as Rawson Court in 1956. The house no longer survives.
The “Reaghill” Homestead
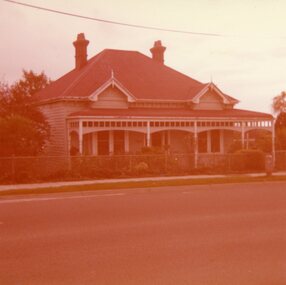
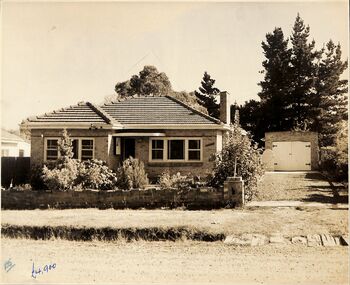
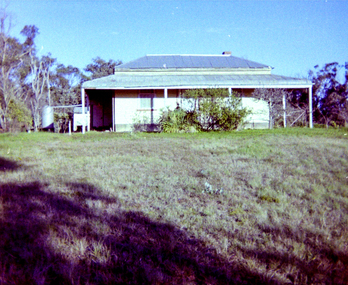
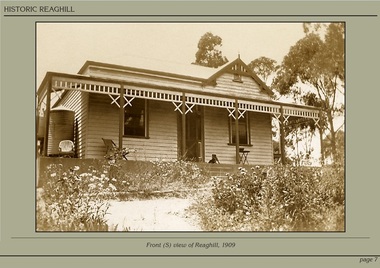
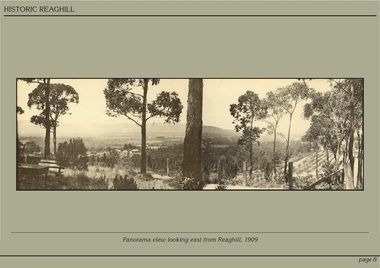
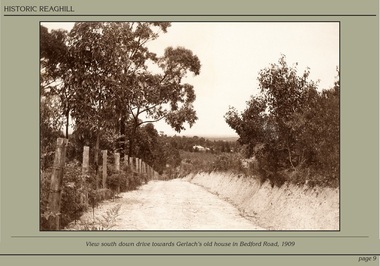
The original homestead on Wallace Bruce’s holding, as has just been described fronted Canterbury Road in the area which is now Rawson Court. The age of the house is unknown but is described in 1914 as being “old and rambling”. The “Reaghill” homestead is likely to have been built by the Davies and was retained on Lot 11 of their subdivision. Its date of construction is not known but might have been soon after the Davies bought the land in 1909. Lot 11, with “Reaghill” was not sold in the 1950s as part of the land subdivision and sale. It remained as the family home of Dr. Davies until its sale in 1968 (without the 15 year covenant) to James Hamilton Kelly of New York, USA for $15,000. In time, Lot 11 was resubdivided. The house today remains on a reduced site of 7112 square metres, still on the highest point in the locality with fine views.
Further Subdivisions
Once the 15 year time frame of the covenant expired, the various owners of the lots, having built homes, proceeded to subdivide their surplus land. Lot 1 was first, followed by Lot 7. Only four of the original 15 acreage lots have not been subdivided. Some subdivisions were less respectful of their environment and neighbourhood than others. Maroondah City Council's planning scheme provides for a minimum lot size of 864 square metres in the locality. But the horse has already bolted.
Summary
“Reaghill” in its heyday, and the acreage properties which later surrounded it, contributed some of the finest and most exclusive properties in Ringwood East. Notably, the locality was home to a significant number of local medicos over the years. Its location dose to the newly relocated Tintern CEGGS gave it added exclusivity.
Subdivision over the years has impinged on the beauty and the environment. However it is still a most important part of Ringwood East, with a rich history.
R.A Carter
January 2005